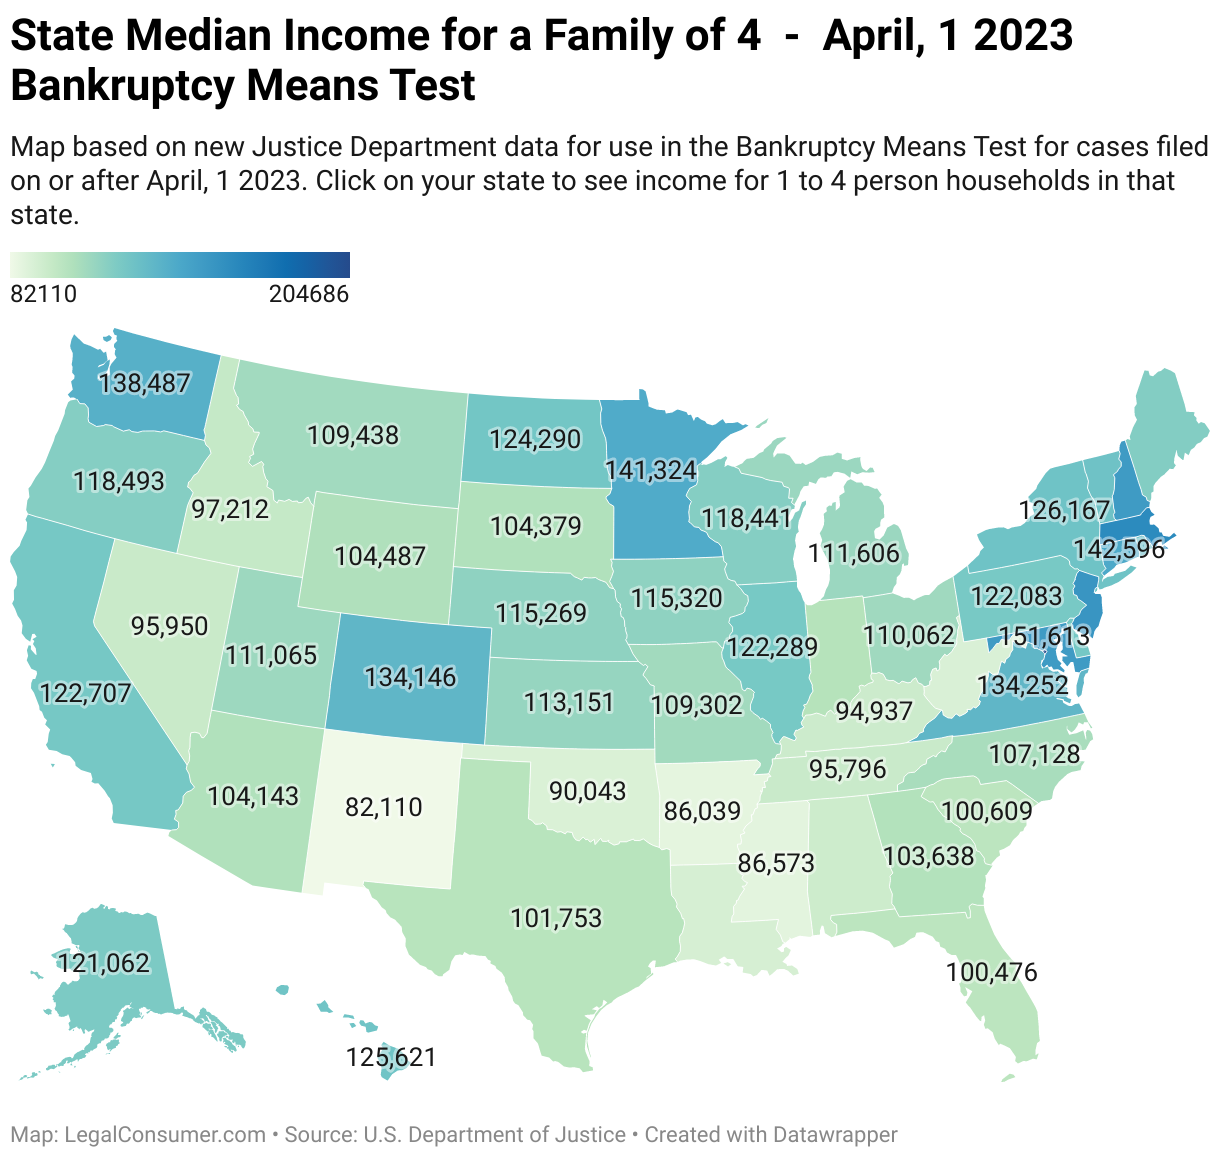
Our plan payment is $610, with $511 (or is it $512?) going to our car payment, the rest goes to attorney & trustee fees. We're in 0% payback, but we are $20k below the median for a family of 5.
Like pp mentioned, you really can't go off of other people's payback though. There are just too many factors. Income varies from plan to plan, as does what is included in the plan. For example, someone who is paying all their secured debt into their plan, including mortgages, is going to seem like they have a super high payment to someone who pays their secured debts outside the plan. Also, some people are choosing to keep non-exempt assets, or have mortgage arrears, or IRS debt, and therefore have a minimum that they have to pay in. It's quite complex, really.
-
The amount is different for everyone depending on yearly income, amount of debt owed, disposable monthly income determined with the means test and other factors you need to discuss with an attorney. Everyone's percent payback is different. Some very little and some substantial. The idea of bk13 is the creditors get something and it is not a magic wand to erase all your debt. It is a reorganiziation of your total debt over a three to five year period within your ability to repay any or all of your debt.I'm really trying to find information about how much people are paying to the trustee each month. I think that would give me more peace of mind to know it's not going to be $5000 or something insane.
Our monthly payment is $1,050. Our yearly income is $80k. We have a crammed down car payment in our plan and our unsecured creditors will get 63% of what was owed.Leave a comment:
-
Originally posted by needanswers View Post
Yes, I have. I passed the first time, failed the 2nd time. We are submitting our information to our attorney on Monday and should have a "quote" on Tuesday or Wednesday. I'm probably just freaking out for no reason, but until we get our offer I'll be a wreck! Thanks for everyone who has responded. Keep the advice coming. It's been so helpful!
Leave a comment:
-
Have you taken an online means test to get an idea? We went to our attorney interview prepared with our monthly expenses and paycheck stubs and we got a ballpark figure.
Originally posted by cspa522 View PostLeave a comment:
-
I will say that one encouraging thing for me is that we have gone 15 months without using credit cards, with the only exceptions being at Christmas when we used a Kohl's charge and a JCPenney's charge here and there. But that's IT. Nothing else. So living without them will not take any getting used to. Though I will deeply miss my Kohl's charge and the great coupons you can only use if you have their charge card!!Originally posted by andy158 View Post
Another thing we've discussed is taking the money we save and converting it to prepaid Visa's or Visa gift cards simply so that if we need to get a repair done we can use that instead of cash. You can get those at our neighborhood Walgreens, and makes me feel safer than having a ton of cash lying about the house.
I'm really trying to find information about how much people are paying to the trustee each month. I think that would give me more peace of mind to know it's not going to be $5000 or something insane.Leave a comment:
-
Something that helped us was to get things like our car insurance deducted form our checking account every month. Two of our utilities are bi-monthly and we set up automatic withdrawals for those as well each month. The only thing we put money aside for budget wise is our property taxes every six months. We don't get any "surprise" bills. In fact our mailbox is almost always empty
I cannot stress enough to get an emergency fund started immediately. You definately need that. We depleted ours and restored it three times already. That was the one thing that scared us was no cc's to fall back on in an emergency. Been a year now and we are doing fine. A lifestyle change is a must and we have learned to live without a lot of unnecesary things.
We still shop on line using PayPal and MoneyPax instead of cc's. You have to have the cash before you can buy. A good way to set limits.
We are not "scraping" by, but living like we should have been all along. Our plan payments are very livable and when it is finally over, the payments we are making now will make a nice savings each month for big ticket items to be paid for in cash.Leave a comment:
-
Um, yeah, I was thinking the same thing myself! You want an attorney on your side, not the creditors.
Originally posted by momofthree View PostLeave a comment:
-
How will we pay our personal property and property taxes in December (our property taxes are not included in our mortgage right now, nor is insurance)?
Our taxes aren't included in your mortgage payment, either. We have to set aside money from paychecks to pay this when it's due.
If we have an emergency, such as our furnace goes out, how do we pay for that?
The first thing you want to do is start building up your emergency fund. You wont have credit cards to fall back on for emergencies. Living without credit is tough, extremely tough! But it can be done!!!!!
How much money can we remove from our checking/savings prior to filing or during the filing process?
You should not go making large withdrawals right before you file or if you do, be ready to explain what you're using the money for. We made large withdrawals to pay the attorney.
Are we allowed an entertainment budget for a dinner out?
Seems like this varies by trustee. We claimed a small entertainment amount of $25-$30/person for a family of 5.
Are we allowed to budget in for birthdays and Christmas?
This would probably be tied into your entertainment budget.
What if we receive raises during the process?
Seems like 10% seems to be the magic number. If it increases more than 10%, from what I have read, it needs to be reported. Probably also varies by trustee.
Can I change the amount I give to my 401k before or after filing? I’d like to increase it.
You should ask your attorney about this. At my 341, I saw a couple get ripped apart for increasing their 401K at the time of filing. The Trustee was NOT happy.
I need to buy 2 new tires, can I do that before we file (with cash)?
Do everything you need to do to maintain your property/cars before you file. If you have quite a bit in your savings/checking because you're not paying the credit cards, stock up your pantry.Last edited by needanswers; 08-20-2010, 05:56 PM.Leave a comment:
-
I would say if you are able to save a thousand dollars a month than your attorney is doing an EXCELLENT job! The attorney is on your side, to ensure that you are able to keep as much as possible, within the construct of what is legally allowed. Unless you have mortgage arrears or other priority debt to repay, your attorney should not be concerned with "not paying enough" to your creditors.Originally posted by cspa522 View Post
I agree with other posts... might want to see what some other lawyers have to say before you commit to this one.Leave a comment:
-
I'd interview a few more attorneys. If the attorney is already saying that she hasn't done her job right if you have extra money each month, then it doesn't sound like she is the type who will fight for you and be 100% behind you and looking out for your well being.Originally posted by cspa522 View Post
But, also keep in mind that technically, on paper, it will not look like you're saving money each month. You're simply setting money aside monthly for yearly expenses that will occur at a later date.
Also, it's not a law or "official rule" that you have to have new cars to file ch.13. They'll let you file even if you only have a beater that barely runs. However, as a general rule, a ch.13 debtor needs to have reliable transportation and since the courts allow a payment, it's best to take advantage of that in order to decrease your chances of having major mechanical difficulties during your plan years.Leave a comment:
-
Okay. Maybe it's different in my state. The attorney I've spoken to told me that if were saving a thousand dollars a month than she hasn't done her job correctly and we're not paying out enough to our creditors/repayment plan. She also said we shouldn't have more than $1000 in our checking and $1000 in our savings when we file. Since we'll have stopped paying our bills, we're going to have more than that for sure.Originally posted by momofthree View Post
Then again, we haven't had the official paperwork drawn up yet. We're still in the gathering mode, getting her our paystubs and list of creditors, etc.
However, here's another question - does the case get reviewed every quarter/year/something? If I have $5000 in savings, how will the trustee know?
I feel like a snot, but I just don't want to live the next 3-5 years scraping by. I've BEEN doing that and it's led me here. The oldest care we have is a 2002 Jeep Liberty, that I'm sincerely hoping makes it the next 3 years. But we shall see. It must be new enough because the lawyer didn't mention it was too old to qualify us. And when I asked what would we do if the car just died on us, she said we'd appeal to the courts to let me try to get a loan for a new, small vehicle to get us through (which is fine by me).Leave a comment:
-
Here is a list of Missouri bankruptcy exemptions:Originally posted by cspa522 View Post
They don't allow much cash on hand at the time of filing. BUT, like SM mentioned above, in a ch.13 that just sets a minimum that you have to pay into the plan. If you have $5000 in a bank account at the time of filing and can only exempt $1000 of it, then you just have to pay at least $4000 over 60 months in order to keep that money. Based on your statements here, I don't think that will be a problem for you.
Also, you can save as much as you want after you have filed. If you don't have the cash on hand when you file, you'll have to hope that your furnace doesn't go out right away, because it will take you several months to build up that emergency fund, but as long as you stick to your budget, cut back where you can, and save any extra money you have, then you'll have plenty of money in savings in a short amount of time. Well, as long as murphy leaves you alone for a little while.
Also, don't know how old your cars are, but one of the major rules of filing a ch.13 is that you need to have new cars that will get you thru 5 years without needing repair. The trustee will allow you 2 car payments of less than $496 each.Leave a comment:
-
WOW - thanks! That makes me feel SO much better. I have just been completely freaking out that we'd have $30 left over each month. I'm not asking about this so we can budget for a vacation or anything, but I have 2 kids. And a house. Things come up - unexpected school expenses, my car's engine blows up, the cat gets sick. And I'm not a fashion plate, but I do work and am expected to wear business casual clothing, which needs to be replaced now and then. (like once a year, maybe, do I "have" to get anything)Originally posted by momofthree View Post
THANK YOU!Leave a comment:
-
Thanks. One of the questions I have down to ask is how much outside of the budget we can have in our accounts. If our furnace goes out, I'm going to need something.Leave a comment:

Leave a comment: